Acknowledgement

Here is a list of steps to attempt to get the attention of people who misinform citizens.

1. Email
2. Social media message
3. Postcard
4. Letter
5. Certified letter, return reciept requested
6. Visit, in-person, whistle stop

Further steps (if necessary) might include cash, merciless berating and singing telegrams.

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Wednesday, March 27, 2013 2:50 PM
To: José Quiñonez, executive director, Mission Asset Fund, and chairperson, Consumer Advisory Board, U.S. Consumer Financial Protection Bureau
Subject: The right thing

You wrote: “Experian, a major credit reporting agencies[SIC], estimates that 66 million Americans are unscoreable[SIC]—they do not have enough credit history to generate a credit score. And without a credit score, they can’t get loans to buy cars, start businesses, get mortgages, rent apartments, or even get jobs.”

However, Experian also states, “Employers never get a credit score.”

So, where did you get the idea that employers use credit scores?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342
Greece

Earlier this month, credit score company Fair Isaac promoted a social media message by a woman in Greece who claims, inaccurately, that employers use credit scores.

Employers do not use credit scores.

In her story, which is dated 2010, the writer states, inaccurately:

One area which may be controversial for a fico score to be considered is when they are used by potential employers. Some positions are dependent on a good score, and not measuring up could end up costing you the job you want. Again they are used to assess your reliability and can indicate how responsible you are.

In 2010 news agency Reuters furthered the employers-use-credit-scores myth when it interviewed the Fair Isaac CEO and reported, “FICO officially frowns on the fact that employers, landlords, and the like obtain access to individuals’ credit scores and use those scores as a proxy for that person’s general moral upstandingness.”

Prior to that article, regarding its information about credit scores and employment, Fair Isaac responded to creditscoring.com that it used “anecdotal information gleaned from public sources such as published articles.”

Reuters has not made a correction.

Unicameral

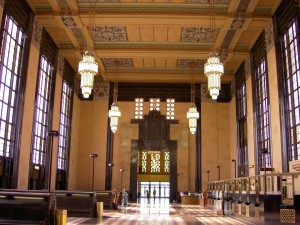
In planning another whistle stop trip, the train to Lincoln (California Zephyr) seems feasible.  But terminating in the capital and bypassing Nebraska’s nearby major city means foregoing another opportunity to experience what appears to be a majestic large public space in Omaha, the Union Passenger Terminal Great Hall.

photograph, Union Passenger Terminal, Omaha
Union Passenger Terminal, Omaha

The manager of the Lincoln Marriott, however, makes staying in the capital city, at least, a comfortable choice (assuming the senator does not reply).

Getting to North Platte?  That’s another story.

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Thursday, February 21, 2013 1:09 PM
To: Annette Dubas, state senator, Nebraska
Subject: credit score, employers, Nebraska Unicameral Legislature

A report quotes you saying, “The use of a credit score in job applications has an especially negative impact on women, the disabled, and certain populations such as Hispanic and African Americans because their scores tend to be lower.”

Employers do not use credit scores.

What will you do to correct the record?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342
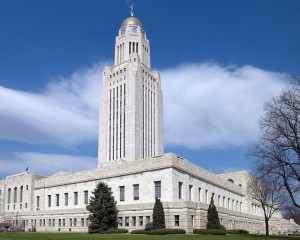
Nebraska State Capitol building
Nebraska State Capitol

Bad reporting at the Washington Post

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Wednesday, February 13, 2013 11:44 AM
To: Michelle Singletary, columnist, Washington Post
Subject: Your bad reporting

See this message and your response (or lack of it) at https://blog.creditscoring.com/?tag=washington-post-company.

You wrote, “The information is then used to create credit scores, which can affect consumers’ ability to get a credit card, a home loan, an apartment or even a job.”

Employers do not use credit scores, and you failed to substantiate your claim.  Did you just make it up?

Who is your source?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342

30, 30

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Friday, February 08, 2013 4:08 PM
To: John Branham, public relations and social media manager, TransUnion Interactive, TransUnion
Subject: 30, 30

See this message and your response at https://blog.creditscoring.com/?p=4657.

Your press release states, “A history of late payments – even by a few days – can potentially harm your credit score.”

However, according your key, an adverse rating only begins at 30 days.  By “a few days,” do you mean a month?  And, couldn’t just one late payment harm a score?

Also, what is so healthy about keeping balances “at or below 30 percent” of a person’s total available credit?  Did you poll lenders?

Finally, what are you doing about the inaccurate USA Today report?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342


Prediction: USA Today publisher Gannett will make a correction

USA Today publisher Gannett will make a correction to its latest story about credit scores.  You can believe that prediction because it isn’t easy to get around fundamental numbers.

USA Today claims that the VantageScore credit score scale is 501 to 999 when it is actually 501-990.

But, McPaper is in good company. Testifying before the U.S. House of Representatives, VantageScore chief Barrett Burns committed the same error twice, according to the official record.  VantageScore’s account of history is peculiarly different.

Further, Gannett will make a correction because the company has never come to terms with its inaccurate story about employers and credit scores.  The newspaper’s response was to use the pathetic and annoying “Read the story again” strategy.  Its editorial department (fine people, all) is, thankfully, cooperative and much wiser.  Happy Groundhog Day, by the way.

The numbers journalists use to add credibility to their stories are the same ones that can come back to bite them.

Revolution Capital Group, LLC and the Tampa Tribune

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Friday, February 01, 2013 11:01 AM
To: Robert Loring, founder and managing partner, Revolution Capital Group, LLC; William Barker, publisher, Tampa Tribune; William Barker, publisher, Tampa Tribune (2)
Cc: Chris Ingram, president and founder, 411 Communications; Nancy C. Detert, chair, Committee on Commerce and Tourism, Florida Senate; Regan McCarthy, senior producer/assignment editor, WFSU-FM/ Florida Public Radio
Subject: RE: Florida Senate Committee on Commerce and Tourism, Revolution Capital Group

See this message and your response at https://blog.creditscoring.com/?p=4630 and https://blog.creditscoring.com/?tag=florida.

You published, “So the Legislature is here to save the day because Detert has apparently deduced that people are unemployed because they can’t get a job because of the bad economy, which caused them to pay their J.C. Penney bill late, which caused them to get a lower credit score, which employers are using to deny them jobs they would otherwise be hired for.”

Employers do not use credit scores.

Your policy is to correct all errors of fact.

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342

[email to WFSU attached]

Optimal credit utilization ratio

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Monday, January 28, 2013 2:15 PM
To: Charles J. Phelan, Credit.com
Subject: Optimal credit utilization ratio

See this message and your response at https://blog.creditscoring.com/?p=4627 and https://blog.creditscoring.com/?tag=utilization-ratio.

You wrote, “The hidden problem with carrying credit card debt balances is that as the balances climb, you will eventually exceed the optimum credit utilization ratio, and this in turn will lower your overall credit score.”

What is the optimal credit utilization ratio?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio 45409-0342

Out of 850

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Thursday, January 24, 2013 9:22 PM
To: Blake Ellis, personal finance writer, CNNMoney.com
Subject: credit score, myth, out of 850

See this message and your response at https://blog.creditscoring.com/?p=4607.

You wrote, “For example, while a FICO score of 790 out of 850 is considered excellent, it’s merely mediocre on the VantageScore model — which tops out at 990.”

So, would you refer to a FICO credit score of 301 as 301 out of 850?

What is your correction policy?

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342

Myth within myths lists

“It is a riddle wrapped in a mystery inside an enigma; but perhaps there is a key.” – Winston Chrchill

From: Greg Fisher [mailto:greg@creditscoring.com]
Sent: Wednesday, January 23, 2013 11:30 AM
To: Jeanette Tucker, professor, Louisiana State University
Subject: RE: credit score, employers, Fox Business, Act II, NIH; closing accounts shortens, LSU AgCenter

See this message and your response at https://blog.creditscoring.com/?p=4592, https://blog.creditscoring.com/?cat=335 and https://blog.creditscoring.com/?tag=lsu.

You wrote, “The length of your credit history, however, is important, and closing older accounts could reduce your credit score.”

However, consumer reporting agency Experian explains, “Contrary to popular reports, you don’t lose the positive credit history when you close an account.”

I was wondering if you’d like to comment on this confusion.

—
Greg Fisher
The Credit Scoring Site
creditscoring.com
PO Box 342
Dayton, Ohio  45409-0342

[another email thread was attached to that message]